Pay off student loans or invest? A decision map
Pay off student loans or invest? Here's the order I'd think about it in, as a capital allocator.
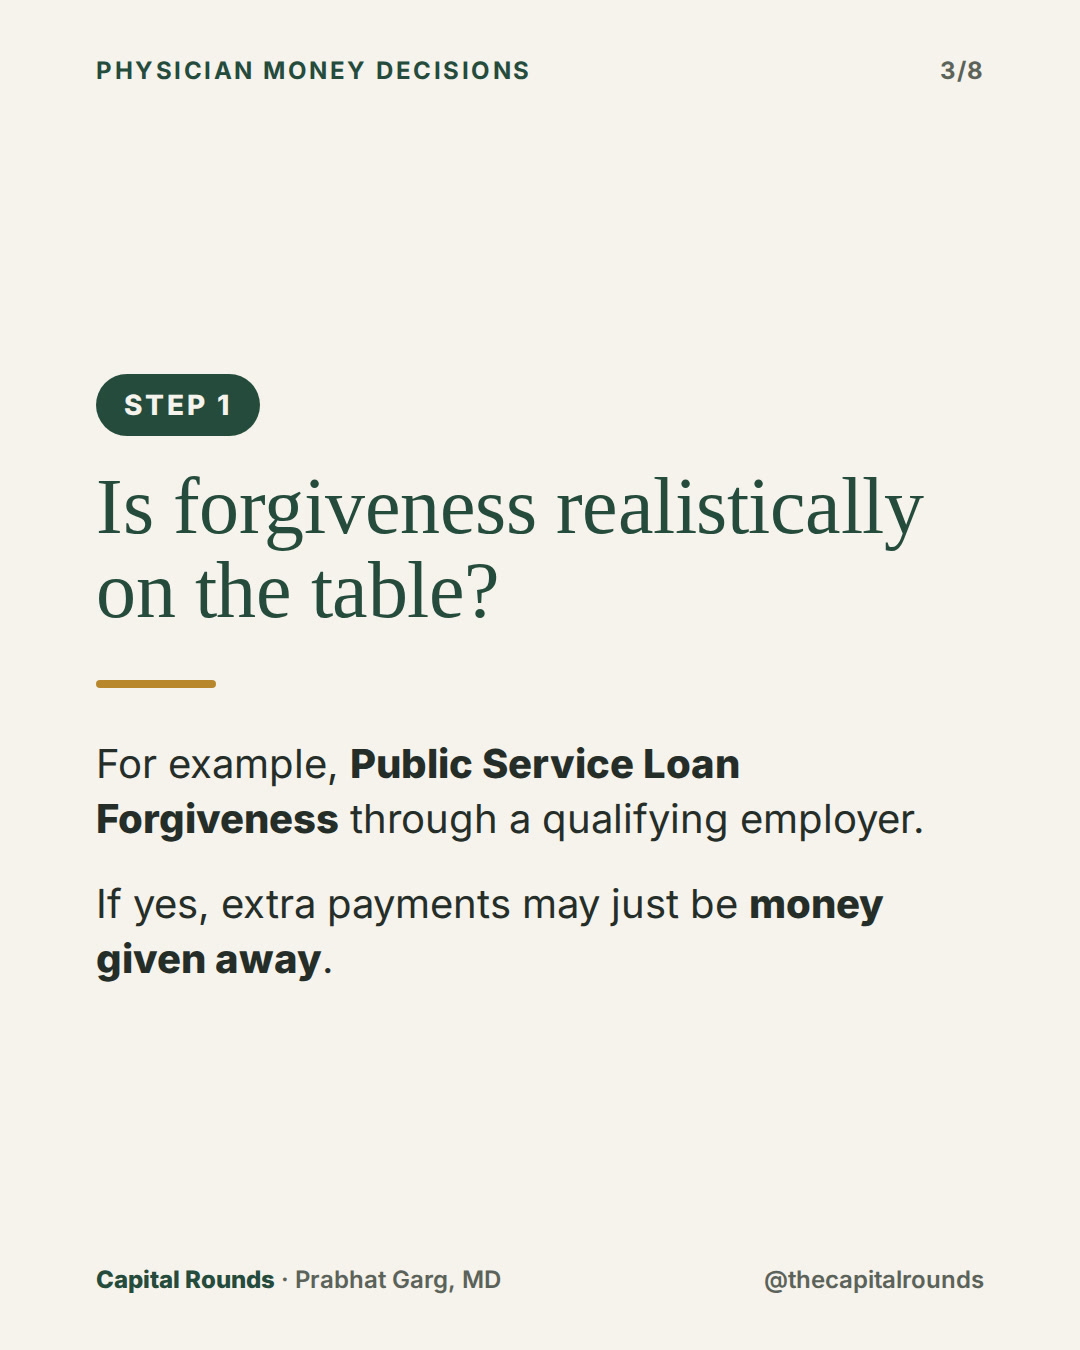
The most expensive mistake is skipping step 1: if forgiveness is realistically on the table, extra payments may just be money given away.
Slide by slide
- Pay off student loans or invest? A capital allocator's decision map
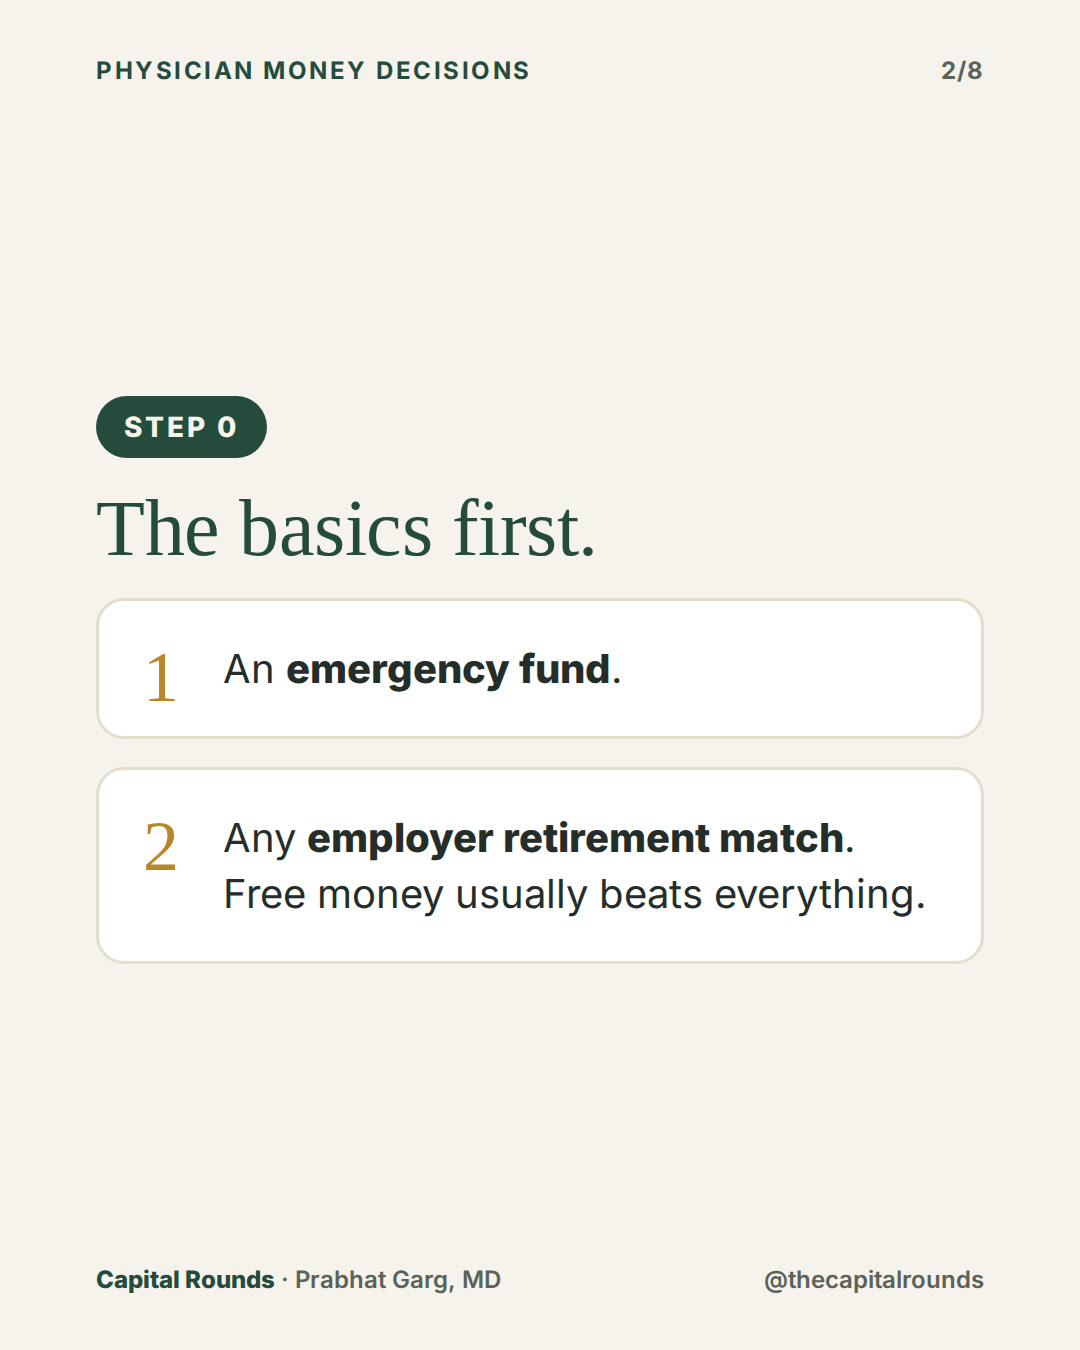
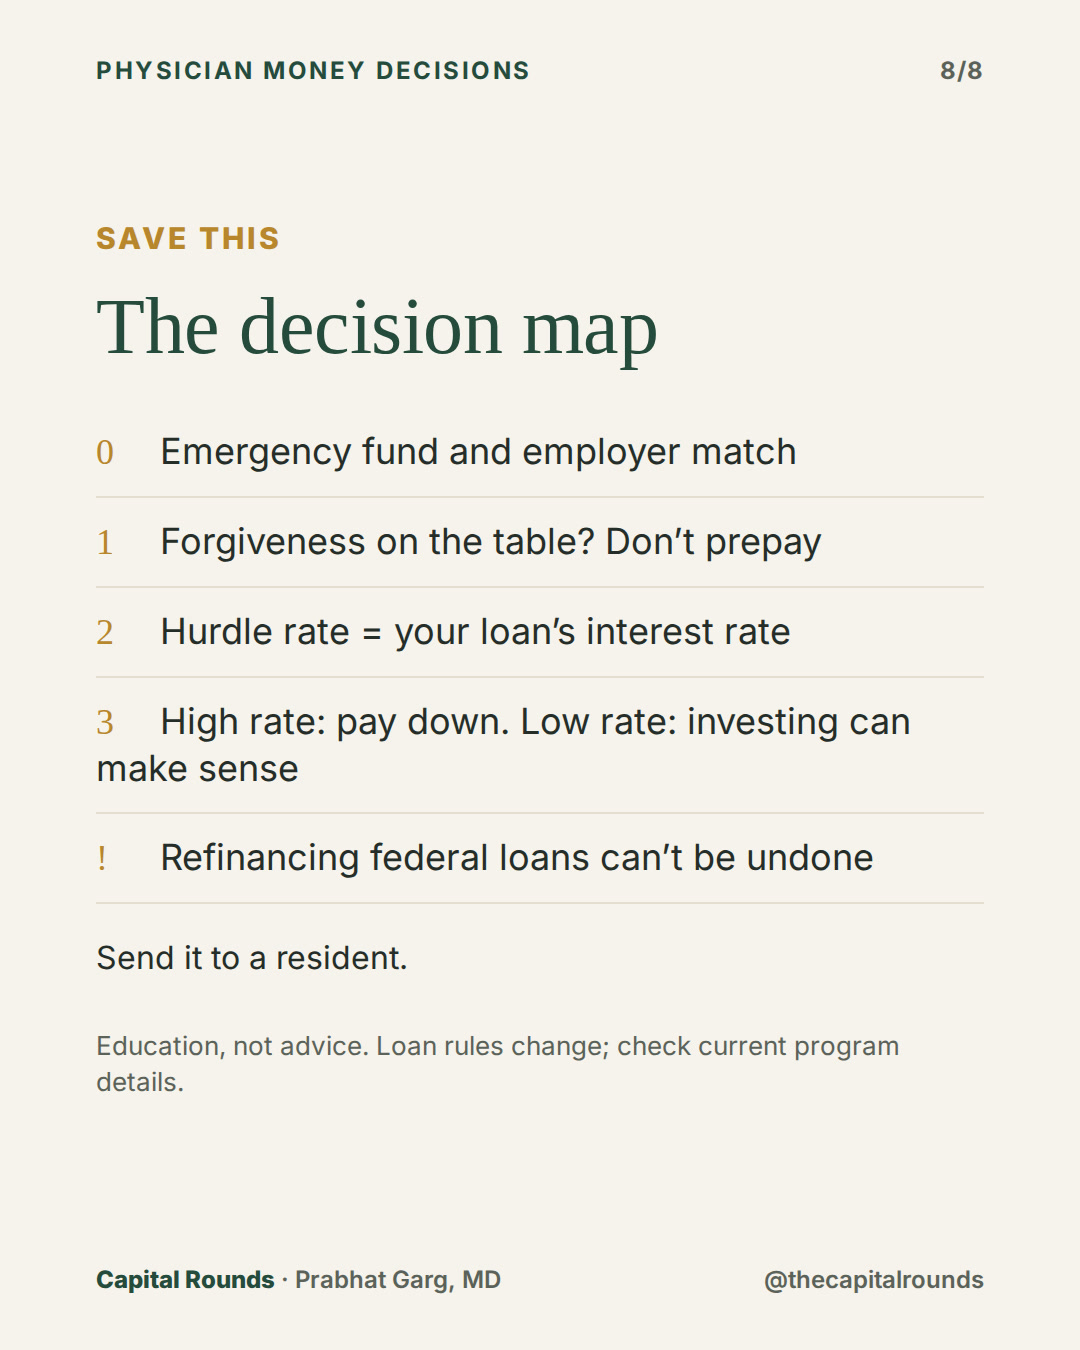
- Step 0, the basics first: an emergency fund, and any employer retirement match (free money usually beats everything).
- Step 1: Is forgiveness realistically on the table, for example PSLF through a qualifying employer? If yes, extra payments may just be money given away.
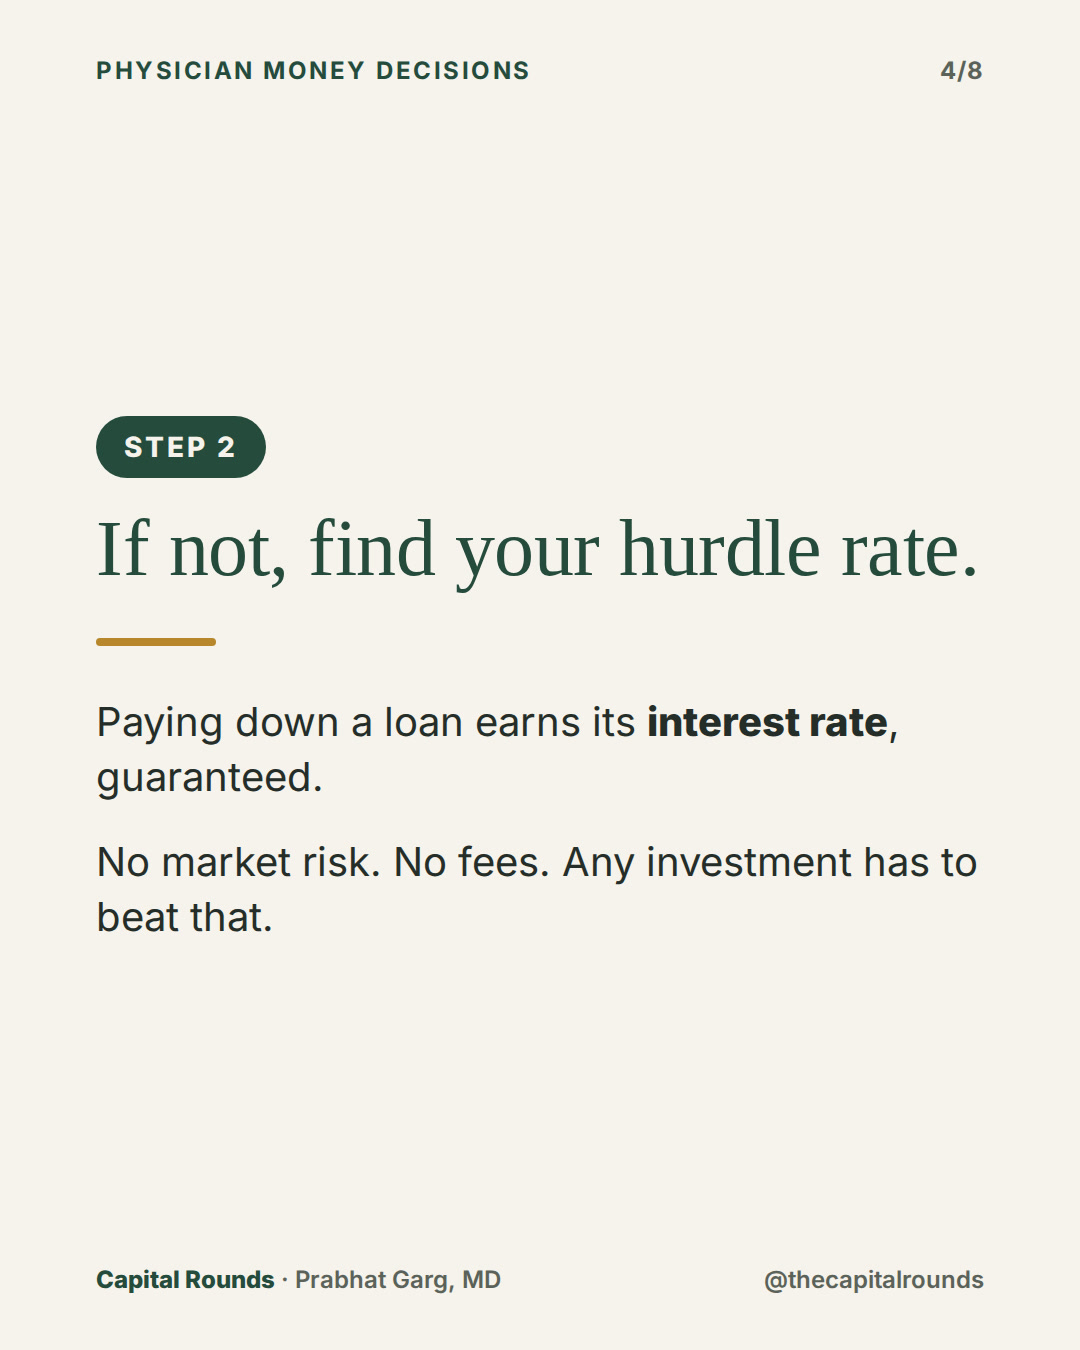
- Step 2: If not, find your hurdle rate. Paying down a loan earns its interest rate, guaranteed, with no market risk.
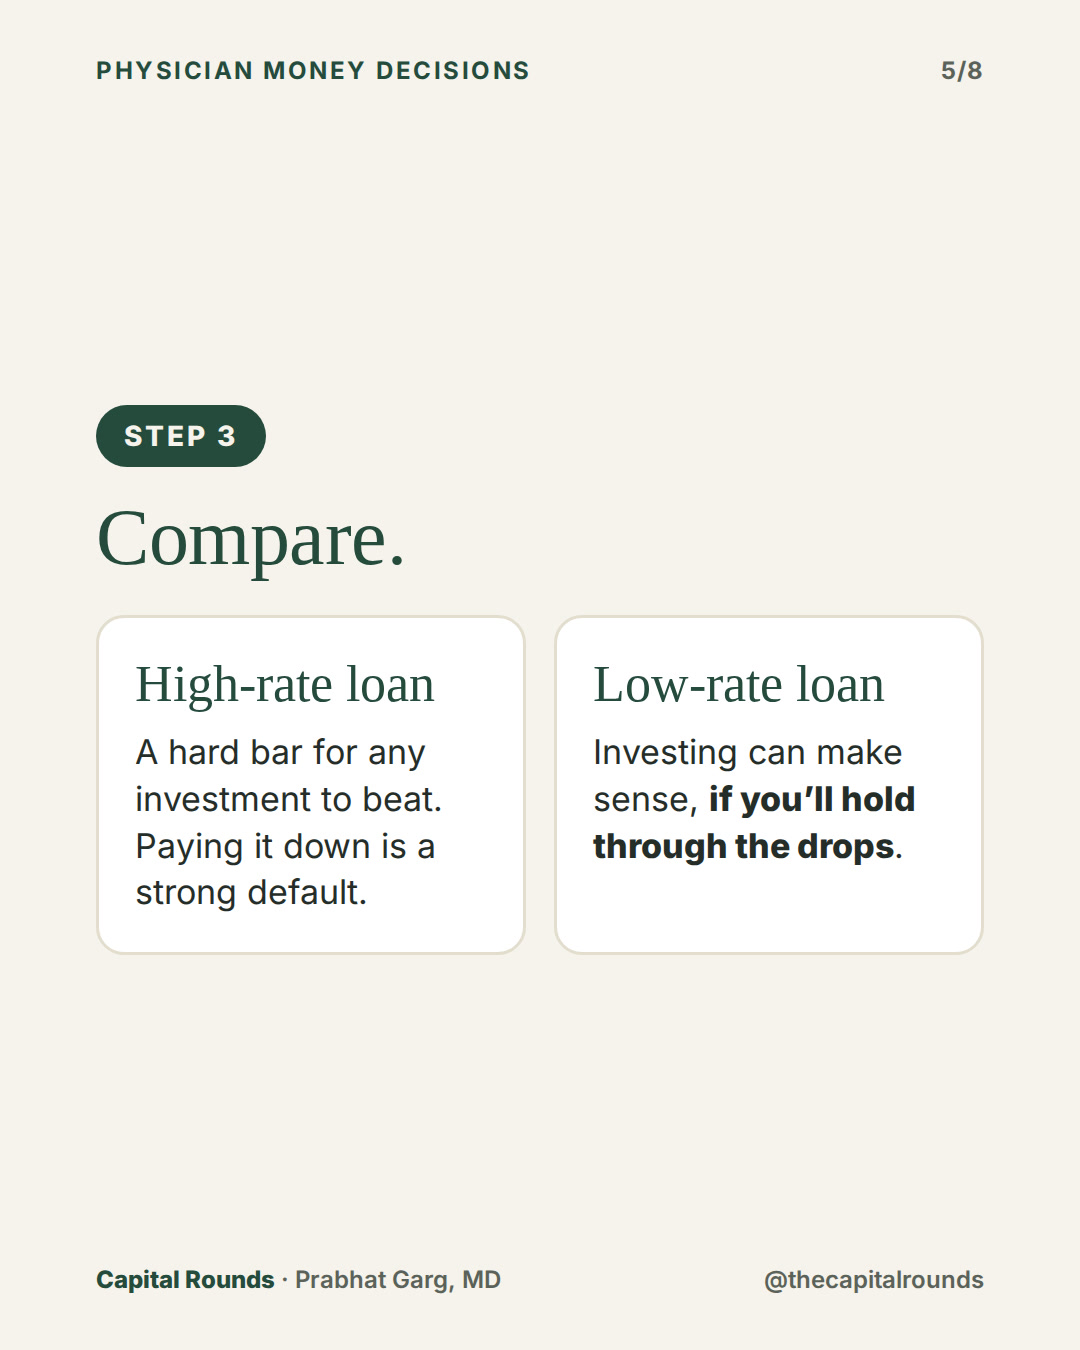
- Step 3: High-rate loan? A hard bar for any investment to beat; paying it down is a strong default. Low-rate loan? Investing can make sense, if you'll hold through the drops.
- Watch out: refinancing federal loans into a private loan can cut your rate but gives up federal protections and forgiveness. It can't be undone.
- Don't forget: being debt-free is worth something. Sleep counts.
Sources
- Public Service Loan Forgiveness: StudentAid.gov
- Refinancing federal loans into a private loan means they're no longer federal loans: StudentAid.gov on refinancing and consolidation
- Loan rules change; check current program details before acting.